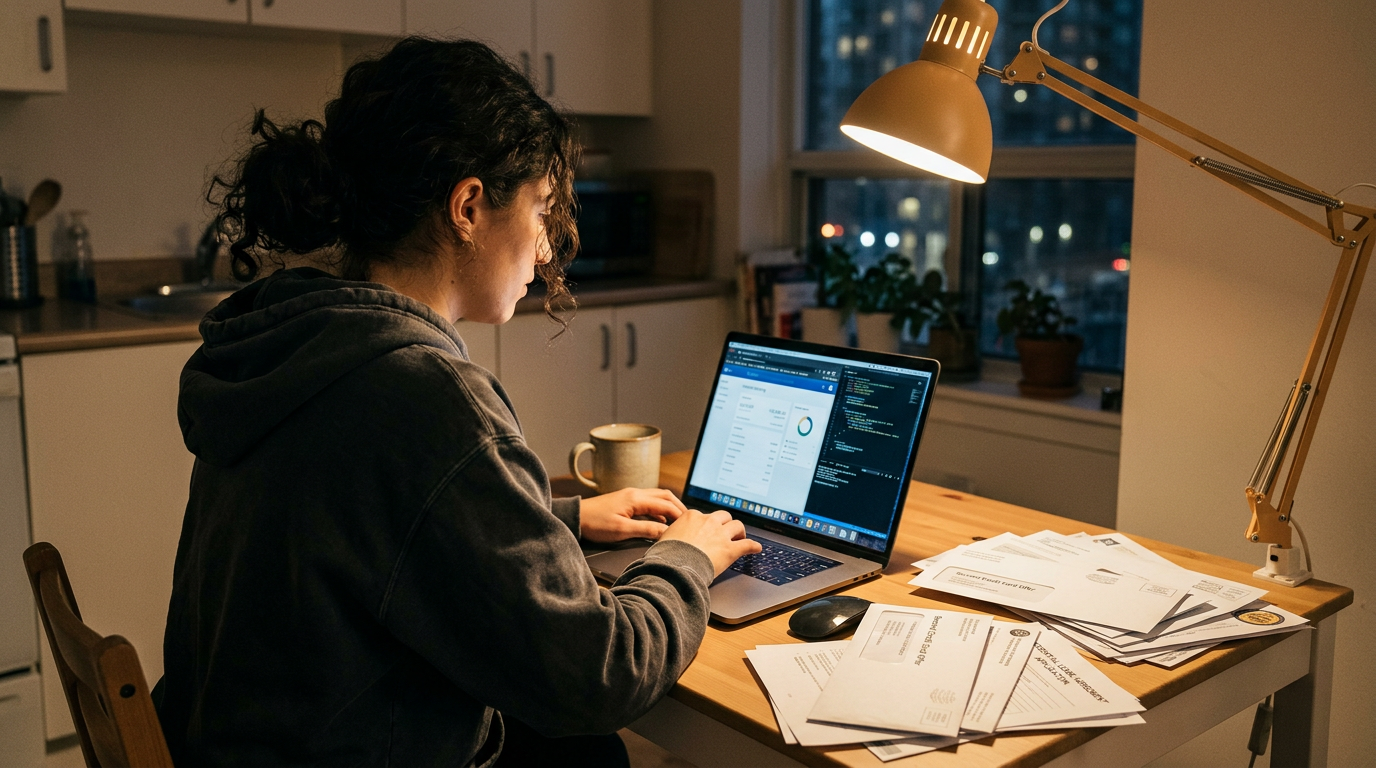
You land the offer letter, sign the contract, and start prepping for your first US assignment. Then you try to rent an apartment and the leasing office asks for a credit score. You try to finance a car and the dealer runs a report that comes back blank. This is not a reflection of your income or your job. It is a thin file problem, and it is completely mechanical to fix.
A thin file means the three major bureaus — Experian, Equifax, TransUnion — have little or nothing to score. No score is not a bad score. But to a landlord or lender running an automated check, no score often reads worse than a mediocre one, because there is nothing to evaluate risk against.
The good news: this is one of the most predictable systems in the US financial world. There is a correct order of operations, and doing it out of sequence costs you money and time right when you need neither.
Why a thin file sinks apartment and car applications
Most property management companies use a scoring model (commonly FICO 8 or VantageScore 3.0/4.0) layered under a minimum threshold, often somewhere in the 600-650 range depending on the market and building class. If the bureau returns no score, many systems default to an automatic denial or kick the file to manual underwriting — which usually means a larger deposit, a co-signer, or paying several months of rent upfront.
Auto financing works the same way. Dealerships route your application through captive lenders who price risk off your score. With no file, you are not quoted a bad rate — you are often quoted no rate, and pushed toward buy-here-pay-here lots with punishing terms.
None of this is personal. It is a system reading an empty field as undefined risk.
The order of operations for your first year
If you arrived this year, here is the sequence that gets you a usable file with the least friction and the fewest wasted inquiries.
- Open a checking and savings account first. You need this for direct deposit anyway, and most banks will not even consider you for a credit product without an existing relationship.
- Apply for one secured credit card in your first one to two months. A secured card requires a cash deposit (commonly $200-$500) that becomes your credit limit. This is the single most reliable on-ramp for someone with no US history, because approval is based on the deposit, not a prior score.
- Ask a trusted family member or close friend with strong, established US credit about becoming an authorized user on one of their cards. This can import their account history — age, limit, payment record — onto your file, often within one to two statement cycles. It works only if the primary cardholder has a genuinely clean, low-utilization account. A messy account will hurt you, not help you.
- Use the secured card for small recurring charges — a streaming subscription, a phone bill — and pay the full statement balance every single cycle. Never carry a balance to try to build history faster. That is a myth and it costs you interest for nothing.
- Let six months pass before you apply for anything else. This is the real unlock. Most scoring models require a minimum of six months of reported history before they will generate a score at all. Apply too early and you get rejected or scored on an incomplete picture.
- At month six, pull your own reports at annualcreditreport.com (the only federally mandated free source) and confirm the secured card and any authorized-user account are reporting correctly before you apply for an apartment or auto loan.
Why stacking hard pulls before a relocation backfires
Every consultant moves at least once in year one — new client site, new city, sometimes a cross-country jump mid-assignment. The instinct is to apply for everything at once right before the move: apartment, car, maybe a second card for the moving expenses.
Each hard inquiry shaves a small amount off your score and stays on your report for two years, visible for about one. Stack four or five inquiries in a two-week window and you can trigger a different problem entirely: lenders and landlords see a cluster of recent applications and read it as financial distress or identity risk, regardless of your actual income.
Auto and mortgage scoring models typically have a shopping-window exception — multiple inquiries for the same loan type within 14-45 days (depending on the model) count as one inquiry. Rental and credit card applications generally do not get this courtesy. There is no deduplication window for a landlord check followed by two credit card applications followed by a car loan inquiry.
Sequence your relocation credit activity. Settle the apartment first, let a few weeks pass, then handle the car. Do not apply for a new card in the same window as either.
Secured card vs. authorized user: the real comparison
| Factor | Secured card | Authorized user |
|---|---|---|
| Speed to first report | 1 statement cycle (~30 days) | 1-2 statement cycles |
| Upfront cost | Cash deposit required ($200-$500 typical) | None, unless the primary account charges a fee |
| Control over the account | Full — you are the account holder | None — you depend on someone else's behavior |
| Risk if things go wrong | Limited to your own deposit and usage | A missed payment on their end can hurt your file too |
| Best used | As your foundation account | As a supplement, not a substitute |
What to check before you apply for an apartment
- Confirm your secured card has at least six months of on-time, fully-paid reporting history.
- Pull your own report in advance so you are not surprised by what the leasing office sees.
- Ask the property if they accept income-based alternatives (pay stubs, offer letter, employer verification) for applicants with limited credit history — many do, especially for corporate relocations.
- Avoid applying to multiple buildings in the same week if you can help it. Space them out or ask the leasing office which bureau they pull before applying elsewhere.
None of this guarantees a specific score or approval outcome — every lender and landlord sets its own thresholds, and outcomes depend on your full financial picture, not just this checklist. What this sequence does is make sure you have a readable file by the time someone is deciding whether to rent or finance to you.
If you are navigating your first year on assignment and want to talk through the practical side of relocating for a contract — not just the credit mechanics — the Josh Pros LLC team is an email away at contact@joshpros.com, or you can browse more of what we have covered at https://joshpros.com.
#BuildingCreditNewToUS #SecuredCreditCardFirstYear #CreditScoreForApartmentRental #ITConsultantFinance #FirstYearInUS #CreditFileBasics #ApartmentApplicationTips #NewToCreditUSA #ConsultantRelocation #ThinCreditFile #CreditHistoryTips #JoshProsInsights
Talk to a real recruiter, not a bot.
We'll tell you the rate, the client, and the terms before you interview. And if we're not the right fit, we'll say so.